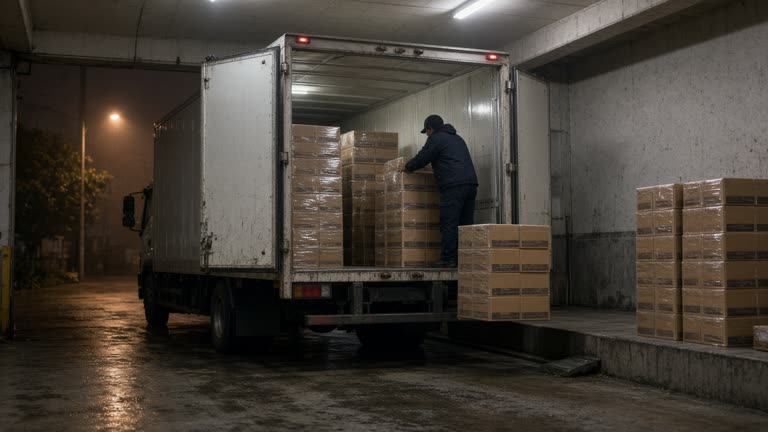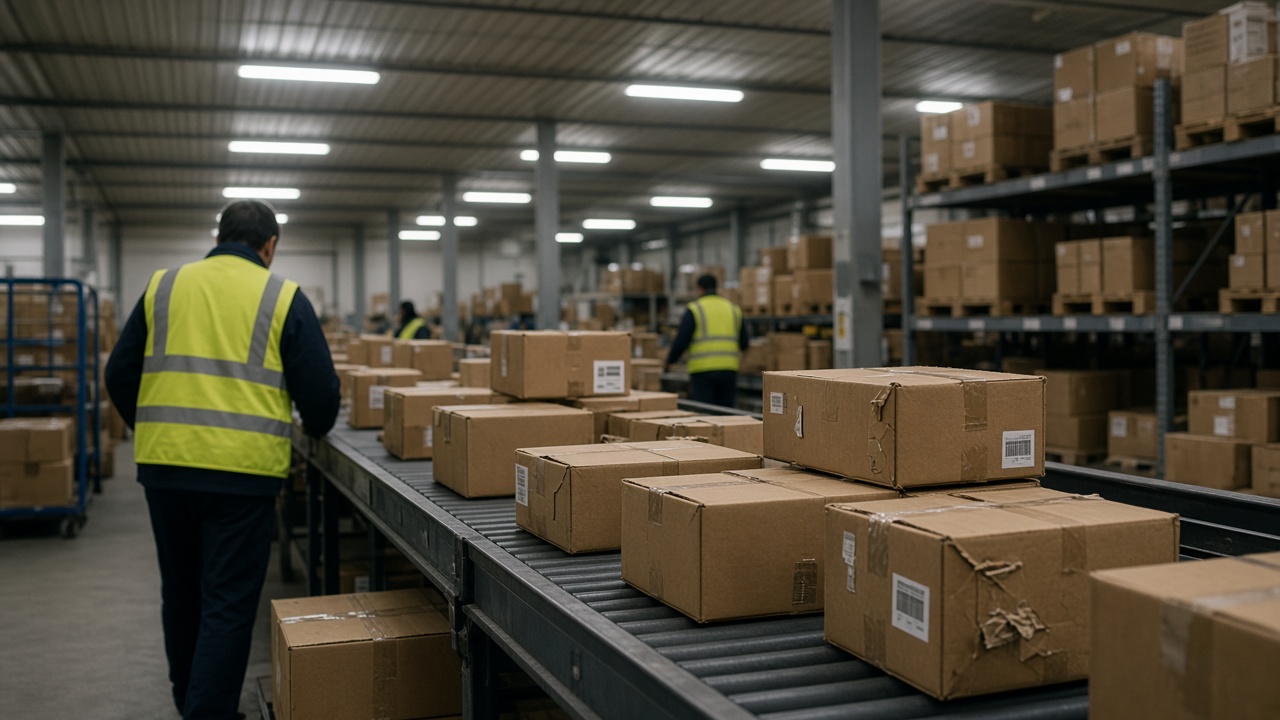
Next plc nudged its full-year profit guidance higher on Friday, telling staff the upgrade owed as much to warehouse colleagues clearing online returns faster as to full-price demand. The retailer’s Castle Donington returns hub—expanded in prior capex cycles—processed a higher share of UK e-commerce refunds without the backlog that store managers complained about last spring.
What the shop floor heard
Area managers in the Midlands received a note alongside the investor statement: stores still take roughly 80% of UK online returns, but the central hub now turns credit notes in fewer shifts. That message landed differently on the sales floor than in the City. Staff at large-format shops said weekend queues at click-and-collect desks shortened once hub scanning matched store intake, reducing the awkward pause when a customer’s refund is stuck in the system.
Warehouse temps hired for peak told the desk they worked split shifts on the returns mezzanine—standard 60x40x30cm cartons account for the bulk of volume—while permanent teams focused on routing mis-sorted footwear back to shelf-ready totes. This was an operational win credited in town halls rather than a bargaining-table settlement.
Why returns drive the number
Next’s trading statement raised group pre-tax profit guidance on stronger full-price sales, but finance directors privately flag returns charge income and lower return rates as margin levers. When refunds lag, provisions swell and customer service hours rise; when the hub keeps pace, markdown risk on returned coats and school uniforms falls.
The CEO’s annual letter already called stores an important part of online service because they absorb most send-backs. International local returns solutions remain patchy—only a fraction of overseas markets offer them—but the UK hub is the template management cites when investors ask about logistics return on capital.
Investors did not get the rota
Equity analysts modelled the guidance upgrade on category mix and finance interest. None of the slide decks mentioned forklift rosters at Donington. Yet operations leaders said the hub upgrade was the difference between a September guidance lift and waiting for Christmas trading. That gap—between spreadsheet drivers and shift patterns—is the spine of this story.
Next also continues to refine delivery-and-returns charging; income from those fees grew faster than sales in recent periods, a subtle tailwind when physical processing costs fall. Hub throughput lets the company hold pricing on small-parcel returns rather than discounting to clear trapped inventory.
Leverage on the warehouse floor
Pickers and returns clerks gained no headline bonus, but overtime caps loosened for six weeks while the hub cleared spring backlog. Managers warned that any slip in inbound parcel trains from carriers would push pressure back to stores, where fitting-room staff double as returns triage. The quiet leverage is timing: faster hub processing means stores spend labour on selling, not apologising.
Seasonal hires said training focused on scanning discipline—matching the SKU inside the box to the customer’s app code—because mis-scans were the main source of duplicate refunds. That sounds granular; at Next’s scale it is millions of pounds of working capital.
Capex the market underweights
Annual filings show tens of millions of pounds still earmarked for returns infrastructure and fleet refresh. The hub is not a one-off project; it is recurring spend to keep pace with online penetration. When Lord Wolfson writes that stores receive most UK returns, he is describing a labour model that only works if Donington keeps up.
International peers without dense store estates must subsidise courier collections; Next’s hybrid model shifts cost to high-street rent that is already sunk. Workers experience that as Saturday shifts scanning barcodes while customers queue for bra fittings next door.
What would change the quarter
A late heatwave extending sandal returns could swamp the hub despite the upgrade. Conversely, lower return rates on full-price womenswear—something management flagged in margin commentary—would compound the benefit. International roll-out of local returns remains slow; UK performance is the laboratory.
Next’s shares reacted modestly in London, in line with a guidance tweak already telegraphed by strong early autumn trading. For workers, the proof is Monday morning: fewer yellow labels piled behind the customer service desk. That is the story investors missed in the PDF.