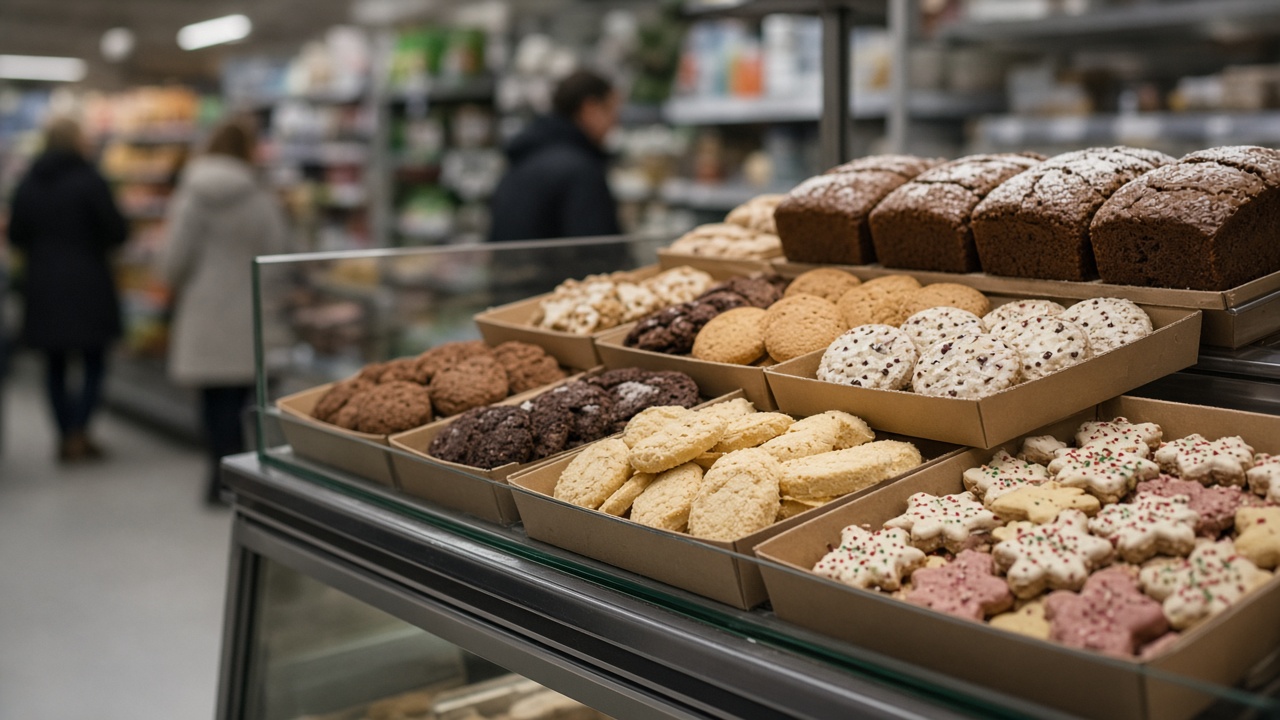
U.S. grocery distributors are reopening private-label margin tables with copackers and retailer commercial teams ahead of the holiday baking micro-season, a negotiation cycle that determines whether store-brand flour, cookie mixes, and in-store bakery items arrive on shelves with the 40-point gross margins executives protected through two years of food inflation.
Who made the call
Category vice presidents at two Top-10 supermarket chains told store-brand suppliers in September that 2026 holiday baking programs would require refreshed cost sheets before October planograms lock, according to people on those calls. The push came from finance, not marketing: private-label dollar sales approached $283 billion in 2025 while national brands grew more slowly, and baking is one of the highest-margin micro-seasons on the calendar.
Workers in retailer headquarters heard a consistent message—protect entry price points on value-tier baking staples while funding premium seasonal SKUs that compete with name-brand gift tins. Copackers said the same buyers who waived specification changes during supply shocks now demand pack-size rationalization and consolidated ingredient lists to simplify plant changeovers.
What employees hear that investors miss
Store managers receive playbooks emphasizing limited-time bakery flavors—peppermint, gingerbread, specialty muffins—that NielsenIQ data show spike each December. Those items carry some of the year's highest seasonal margins, yet they also expire quickly if production runs misalign with weather-driven shopping bursts.
Bakery clerks at regional chains said corporate planners are shrinking the number of simultaneous seasonal SKUs while increasing facings on store-brand cookie dough and pie crusts. The strategy reads as assortment discipline to investors but feels like heavier manual baking workloads to store teams preparing for Thanksgiving and Christmas rushes.
Margin mechanics
Industry commentary puts typical grocer gross margin on national brands in the 25–35% range versus more than 40% on controlled private label. Retailers defend that gap through tiered architectures—value, core, premium—and by owning transaction data that tells them which price points can move without losing basket size.
Holiday baking amplifies the spread because shoppers accept seasonal premiums on items they buy once a year. Distributors negotiating on behalf of independent grocers said copackers are asking for longer payment terms in exchange for holding ingredient contracts on butter and cocoa, while retailers counter with volume guarantees tied to loyalty app promotions rather than upfront slotting dollars.
Brand pushback
National baking brands are not ceding the season quietly. Several manufacturers redeployed trade spend toward digital coupons on core flour bags while launching limited-edition flavors that mirror retailer micro-season calendars. The fight is less about shelf inches than about who funds the impulse purchase at the end of the aisle.
Private Label Manufacturers Association data show store-brand unit volumes still rising even as inflation cools, which gives retailers leverage in September talks. Copackers with excess plant capacity are willing to absorb smaller runs of seasonal shapes—snowflake sprinkles, red-and-green chips—if retailers share forecast files earlier than they did in 2024.
Supply chain details
Egg and butter volatility remains the hidden variable. Buyers are dual-sourcing sweetened condensed milk and evaporated milk for pie programs while locking pallet quantities of store-brand chocolate chips before ocean freight surcharges hit Q4. Some chains are shortening lead times on frozen dough balls so they can react if a warm autumn delays comfort-baking demand.
Distributors serving club-adjacent independents said wholesale-style pack formats are returning to negotiations after a year of focusing on small household sizes. Bulk holiday packs help margin on paper but require different freezer maps in stores built for 12-count rolls, a operational tension category managers are resolving now rather than in November.
What the shop does next
Expect planograms by mid-October to show fewer national-brand seasonal extensions and wider blocks of store-brand baking chips, sprinkles, and ready-to-bake cookies. In-store bakeries will promote combo displays linking flour bags with parchment paper and store-brand vanilla extract, bundles that software tags as margin accretive even if they look like old-fashioned cross-merchandising.
If copackers refuse margin givebacks, retailers have shown they will delist slow national SKUs to free oven time for own-brand items. The holiday baking aisle is where that strategy becomes visible to shoppers long before it appears in a 10-K footnote.