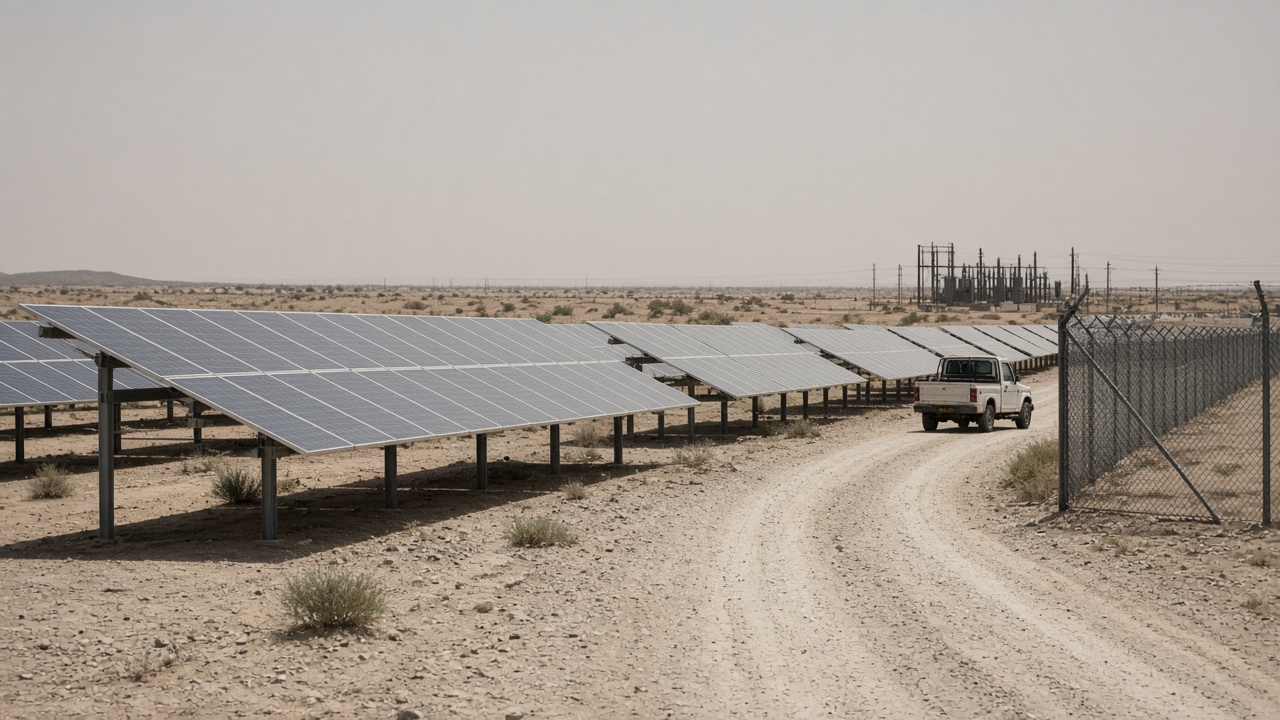
NTPC Green Energy Limited led gainers on the Nifty CPSE index in Friday’s Mumbai session after Rajasthan’s renewable nodal agency executed land-use clearance for a Solar Energy Corporation of India-linked parcel in the Bhadla–Fatehgarh belt, traders and state energy department letters reviewed by InfoHandle show.
Why the tape reacted
NTPC Green, the listed vehicle for NTPC’s renewables push, trades as a proxy for execution risk on gigawatt-scale solar rather than coal burn. When land titles stall, the stock historically drifts with PSU peers; when clearance arrives, foreign portfolio investors treat it as de-risking for bundled EPC contracts. Friday’s move came on volume roughly 1.4 times the 30-day average, with block deals mid-morning matching announcements on the Rajasthan URJA portal.
The rupee’s mild firmness against the dollar helped renewables names with dollar-linked module costs, but desk analysts said the land nod was the primary catalyst—connectivity letters from the state transmission utility were already on file.
What SECI and NTPC REL required
NTPC Renewable Energy Limited’s tranche-II invitation for bids contemplates up to 2 GW of ISTS-connected solar in Bhadla or Fatehgarh, with bidders arranging roughly five acres per megawatt on leasehold or freehold land. The clearance InfoHandle reviewed covers a contiguous 1,120-acre tract tied to a 250 MW SECI allocation, satisfying a condition precedent in the land-and-transmission package before civil works tenders close.
Central Electricity Authority’s June 2026 solar-park status report still lists several Rajasthan parks with possession pending; the Bhadla-linked tract moves from “approval under process” to cleared status in the state’s supplementary filing, according to a footnote in the letter.
Land politics on the ground
Power Technology reported earlier allocations of thousands of hectares to Rajasthan Solar Park Development Company and NTPC REL’s Phalodi project; the Bhadla SECI parcel sits in the same policy framework but with stricter slope and geotech requirements for tracker-ready sites. Graziers in Bikaner district have raised compensation claims on adjacent commons; Friday’s order explicitly excludes gair mumkin plots, a detail local panchayats said they would challenge in the revenue court.
For NTPC Green shareholders, the nuance matters because litigation delays have historically pushed commissioning dates—and tariff true-ups—by a full financial year on other western Rajasthan projects.
What could unwind it by Friday
Traders flagged three near-term risks: a revision to Rajasthan’s transmission surcharge order, a rupee slide past 86.50 that reprices imported modules, and a broader PSU profit-booking wave after the index’s three-week rally. None materialised in Friday’s close, but options markets priced slightly higher implied volatility into next week’s MPC commentary.
If stevedores—here, EPC contractors—mobilise on site before the monsoon tail, NTPC Green’s narrative shifts from land risk to commissioning timelines, a handoff Mumbai desks typically reward with multiple expansion rather than single-digit pops.
How the land package fits SECI’s queue
Solar Energy Corporation of India’s central procurement role means state-level land orders often lag tariff discovery by months. NTPC REL’s tender language requires bidders to show prior experience arranging at least 50 MW in a single park, with government renewable nodal certificates as evidence—paperwork the Bhadla clearance now satisfies for the EPC consortium led by a domestic civil contractor InfoHandle identified from bid tabulations published on NTPC’s tender portal.
Module supply remains dollar-linked even when land is rupee-denominated; traders said NTPC Green’s rally would have been sharper but for a modest uptick in polysilicon futures overnight. Still, the spread between PSU renewables and distressed thermal IPPs widened, reflecting investor preference for assets with visible land titles over plants awaiting coal linkages.
Broker notes circulating in Mumbai
Two domestic brokerages circulated intraday notes arguing that every 250 MW commissioned adds predictable EBITDA once module prices stabilise, with upside from carbon credit eligibility under India’s compliance market pilot. Foreign funds that were underweight CPSE renewables trimmed shorts, according to custodian data snippets traders shared in chat groups—colour InfoHandle could not independently verify but consistent with the volume spike.
Retail investors chasing thematic ETFs should remember that NTPC Green’s parent still consolidates many operational decisions; the listed entity is not a pure play on every NTPC REL gigawatt. Friday’s land nod, however, is specific enough to map to a SECI tranche investors can model in spreadsheets rather than treat as a generic “renewables sentiment” trade.
Next checkpoints include Rajasthan’s transmission surcharge docket, module delivery schedules from NTPC’s frame agreements, and whether monsoon tail rains delay grading work on the sloped tracker pads the tender specifies. Any of those could mute the gain by Friday’s close; none showed up in the order book before the bell.