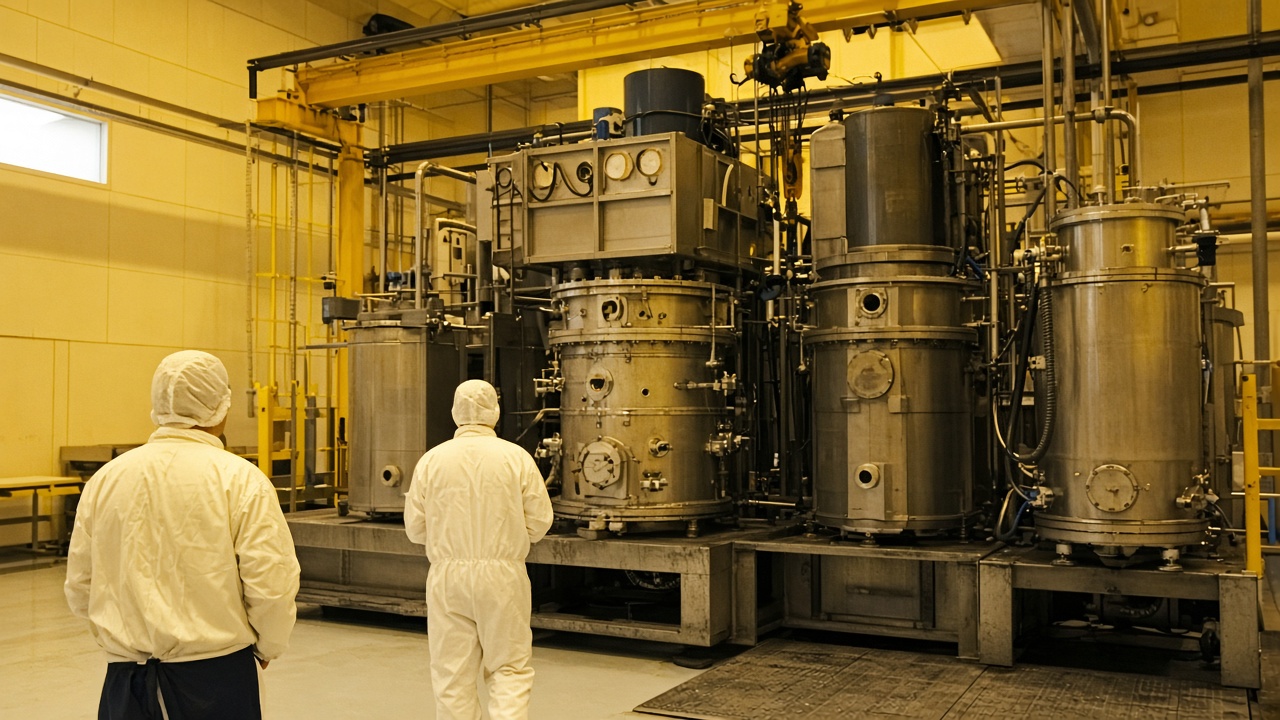
Screen Holdings told analysts it is aligning OLED evaporation tool shipments with a Kyushu display customer’s pilot line startup, booking clean-room install slots for late autumn as the panel maker tests mid-size organic stacks before committing capital to a full Gen line.
Who led and by how much
Screen’s SPE segment guidance for the half implied flat-to-up tool revenue; the Kyushu pilot order nudges OLED evaporation within that band rather than resetting consolidated forecasts, according to investors on the post-guidance call. Delivery windows tightened to six-week crane access at the customer’s Kumamoto-area fab shell, a schedule Screen said it could meet if mask cassettes clear customs without repeat inspection holds.
Display customers globally have slowed large greenfield plans while keeping pilot lines alive for automotive and IT mid-size panels. Screen competes with Korean and Chinese evaporation vendors on uptime and particle specs; winning the Kyushu slot preserves reference status in Japan’s domestic supply chain narratives even when panel ASPs stay depressed.
Mechanism on the floor
OLED evaporation deposits organic light-emitting layers through fine metal masks with angstrom-level registration. Screen’s tools integrate vacuum load locks and in-line metrology the Kyushu pilot will use to compare stack architectures against incumbent LTPS backplanes. Tool acceptance tests hinge on yield within three sigma of golden recipes transferred from Screen’s evaluation lab in Kyoto prefecture.
Clean-room contractors said overhead crane capacity was the binding constraint—not electrical feed—because evaporation chambers arrive as single lifts exceeding fifty tonnes. Screen field service teams will embed two engineers through first light-up, standard for pilot lines where customer process engineers still tweak recipes nightly.
What the street already has in the number
Consensus models Screen’s fiscal year on wafer-cleaning strength plus selective OLED wins, not a display capex boom. The Kyushu shipment is therefore a sentiment stabilizer: proof OLED evaporation demand persists in Japan even when smartphone panel orders oscillate. Bulls argue pilot success pulls forward a 2027 mass-production tool suite; bears counter that the customer can stretch pilot phases indefinitely while burning cash on LCD legacy lines.
Currency matters at the margin: a weak yen helps Screen’s export competitiveness on tool quotes denominated in dollars for overseas customers, while domestic Kyushu contracts settle in yen with parts imported from Screen’s Malaysian module subassembly.
What would falsify by Friday
Any customs delay on mask cassettes or export license paperwork would push install dates past the customer’s public pilot milestone—visible in local prefectural investment bulletins. Screen stock rarely gaps on single pilot tools, but sequential OLED revenue commentary on the next earnings call would wobble if Kyushu acceptance slips a quarter.
Competing panel makers announcing alternate evaporation vendors for the same application would break Screen’s reference story; none have this week. JEITA display shipment statistics showing renewed IT panel inventory builds would support the pilot’s commercial logic; continued inventory digestion would not kill the install but would delay follow-on orders Nina Okonkwo’s desk watches for.
Customer and supplier checkpoints
The Kyushu customer’s capital committee meets after first-pass yield data; Screen sales attached incentive clauses tying service contract renewals to uptime hours, not headline tool price. Logistics teams routed chambers via Hakata port with humidity-controlled tarping after a 2025 incident where condensation voided a week of vacuum pumpdown elsewhere in Asia.
Next steps for investors
Track Screen’s order backlog commentary for “OLED evaporation” phrasing versus generic SPE growth. A second tool PO for the same campus would confirm scale-up; absence would mark the Kyushu line as another Japan pilot that feeds learning without near-term revenue stairs. Until then, the trade is narrow: Screen shipped when the customer needed evaporation capacity to keep a domestic OLED experiment alive while global display capex stays selective.
Supply chain and parts
Screen’s procurement office prioritized vacuum pump rebuild kits for the Kyushu install because lead times on European pump heads stretched after summer maintenance at chip fabs elsewhere in Asia. Substitute parts cleared internal qualification but carry shorter warranty windows—field service budgets for the pilot rose modestly, a line item equity models rarely capture.
Mask suppliers in Japan and Korea allocated cassette slots to the pilot only after Screen guaranteed minimum annual service spend, tying hardware margin to decade-long maintenance contracts typical in semiconductor tools. That structure favors Screen if the customer scales; it caps upside if the pilot stalls after first light-up.
Local subcontractors in Kumamoto prefabricated clean-room wall panels while Screen tools were still in transit, shaving two weeks off parallel construction—a schedule gain the customer highlighted to prefectural officials seeking foreign investment headlines without naming Screen in press releases.