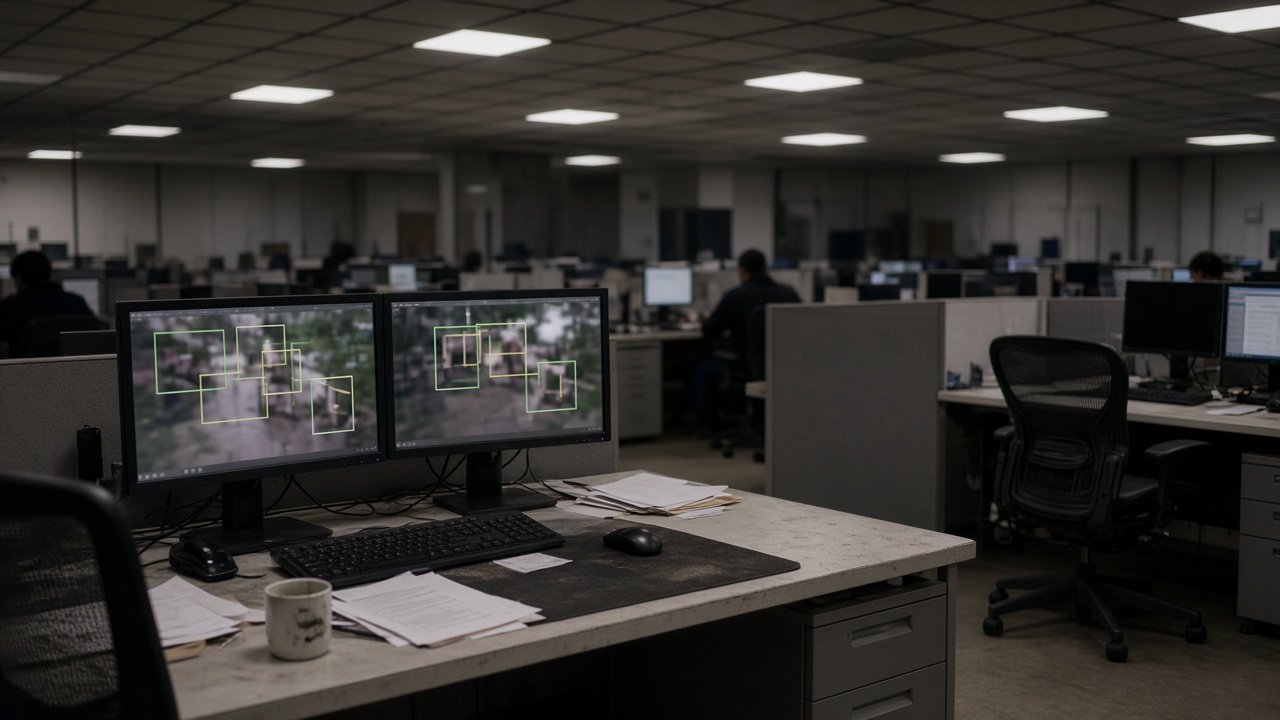
Scale AI restarted secondary valuation discussions with lead investors this month as a Pentagon joint data-labeling solicitation moved to a final down-select that could anchor billions in defense-adjacent revenue over five years. The talks are not a fresh primary round—they set the reference price for employee tender offers and late-stage preferred conversions investors have deferred since Scale trimmed its headline valuation after the 2024 growth equity repricing.
What the RFP actually buys
The solicitation bundles computer-vision annotation, geospatial QA, and safety review for autonomous systems training pipelines across Army and Air Force data shops. Incumbents and challengers submitted fixed-price and cost-plus line items; Scale entered the final round alongside at least one large defense IT integrator and a specialist geospatial firm, according to people familiar with the process who spoke on condition of anonymity because bids remain sealed.
Labeling work is labor-intensive margin business unless software automation raises throughput; Scale’s pitch combines human teams with pre-label models that reduce reviewer hours per frame. Pentagon evaluators weighted security clearance capacity and past performance on controlled unclassified information networks—categories where Scale invested after earlier DIU prototypes.
Valuation talks versus defense optics
Investors tying tender pricing to RFP outcomes bet that a prime award validates Scale’s pivot from consumer gig-work roots to cleared-facility operations. A loss would not bankrupt the company—commercial generative AI data deals still book—but it would weaken the narrative that defense revenue justifies premium multiples relative to offshore labeling shops.
Secondary talks include drag-along mechanics that could force early employees to sell at the tender price if supermajority holders agree; founders negotiated caps on how much common stock must participate, terms counsel revised after employee petitions last spring.
Who gets diluted if the round reprices
New money is not the main event—price discovery is. If tender offers clear at a discount to the last primary, late-stage preferred with ratchets could receive additional shares, diluting common and early preferred unless waivers are negotiated. Meta’s strategic stake and former investor coalition seats complicate governance; some holders want defense wins before signing any down round paperwork.
Employees with expiring options watch the tender window closely; tax timing for ISO exercises depends on fair market value determinations independent appraisers refresh when secondaries close.
Competitive and political risk
Congressional skeptics of AI defense spending question whether boutique labeling firms deserve multi-year ceilings when automated pre-labeling improves monthly. Scale must prove cleared headcount in U.S. facilities, not only contractor pass-through abroad—a sensitivity after prior media scrutiny of overseas annotation labor.
Protest rights remain if losers challenge award rationale; protests freeze start dates and delay revenue recognition Scale may have modeled in investor decks shared during valuation calls.
Bankers advising the secondary said term sheets include a material adverse change clause tied to federal ethics inquiries—unlikely, but the provision shows how tightly defense optics now bind private-capital timing for data-labeling vendors once seen as pure tech growth stories.
Business in one sentence
Scale sells labeled data and review pipelines that make machine-learning models trainable; defense RFPs turn that factory into a clearance-heavy utility whose contract size drives whether investors mark the cap table up or sideways.
What if the next round does not exist
Scale generates cash from enterprise contracts, but growth plans assumed access to cheap capital for compute and headcount expansion. A stalled tender combined with RFP loss could push the company toward profitability discipline—slower hiring, higher automation bets—rather than another primary at a shiny valuation. Founders have not commented publicly on the secondary timeline; people near the talks said closing depends on Pentagon award notices expected before year-end.
What to watch
SAM.gov award postings and protest dockets will move the story before any Form D amendment becomes public. For cap-table watchers, the linkage is explicit: defense labeling volume sets not only revenue but the price employees may sell stock at when the tender finally opens.