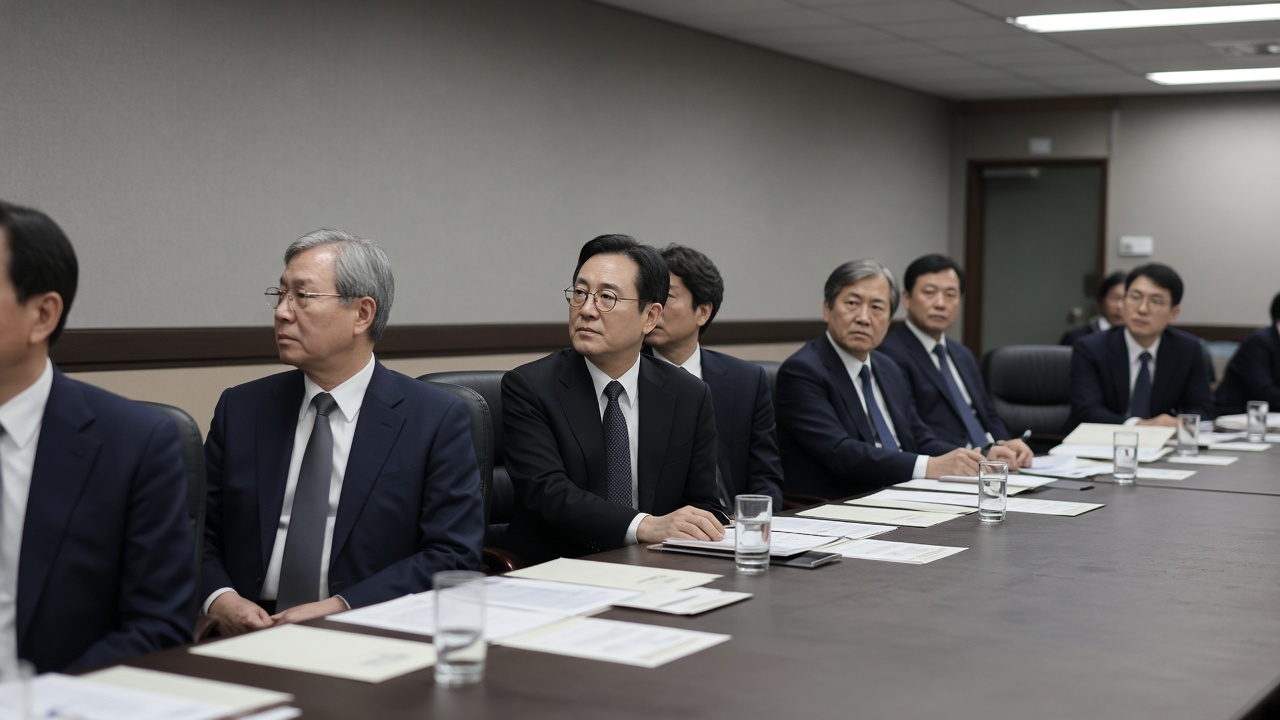
Finance Minister Lee Hyoung-il pulled Bank of Korea Governor Shin Hyun-song, Financial Services Commission Chairman Lee Eog-weon, Financial Supervisory Service Governor Lee Chan-jin and Land Minister Hong Jee-sun into his first joint market session on Friday, two days before a national holiday that will pause equity trading but not the debate over rising Korean government bond yields.
Five trillion won already off the October calendar
The meeting followed a Ministry of Economy and Finance decision to trim Treasury bond issuance by 5 trillion won ($3.64 billion) in October. Lee told reporters the government would consider additional reductions if market stress persists, and that emergency buybacks remain on the table. The package is meant to calm a sell-off that has tracked higher U.S. long-end yields and expensive crude, even as corporate earnings forecasts for the third quarter still look strong on paper.
Lee warned that if elevated rates linger, lower-rated corporate borrowers could face heavier refinancing bills. That message matters for the chaebol-affiliated contractors and mid-tier builders that fund working capital through the domestic bond market rather than cheap offshore dollars. Officials also said they would keep watching apartment prices, noting that Seoul's five-week slowdown in high-end districts has not yet spread evenly to outer wards.
Won internationalization still on the desk
Friday's session also touched on follow-through for won internationalization, with Lee promising regulatory easing steps soon. None of the officials offered a dated legislative calendar, but the remark signals that currency policy will stay paired with bond-market management rather than treated as a separate campaign.
What traders watch after Gaecheonjeol
With National Foundation Day closing the Kospi on Saturday and a substitute holiday on Monday, the next cash session will not test whether Friday's 7,003.74 close holds until Tuesday. Bond desks, however, can still price risk over the long weekend, and Lee's warning that issuance cuts could deepen suggests the ministry would rather shrink supply than rely on a one-day equity bounce to lower sovereign yields.
For households, the more immediate effect is indirect: mortgage repricing and small-business credit lines still key off government bond benchmarks. If yields remain sticky after the holiday, Lee's Friday roundtable may be the first of several supply tweaks rather than a single October adjustment.
Analysts at local brokerages noted that Friday's equity bounce tracked softer U.S. Treasury yields overnight more than any new fiscal detail, which underscores why Lee paired his market message with bond-supply tools. Construction-sector bonds and project-finance notes remain the canary: when those spreads widen, the ministry's warnings about lower-rated borrowers stop being abstract.
Commercial banks said they would relay stress-test results from affiliated consumer lenders after the holiday, a footnote Lee's team did not emphasize publicly but one traders watch because card receivables often reprice faster than corporate bonds.
Commercial banks said they would relay stress-test results from affiliated consumer lenders after the holiday, a footnote Lee's team did not emphasize publicly but one traders watch because card receivables often reprice faster than corporate bonds.