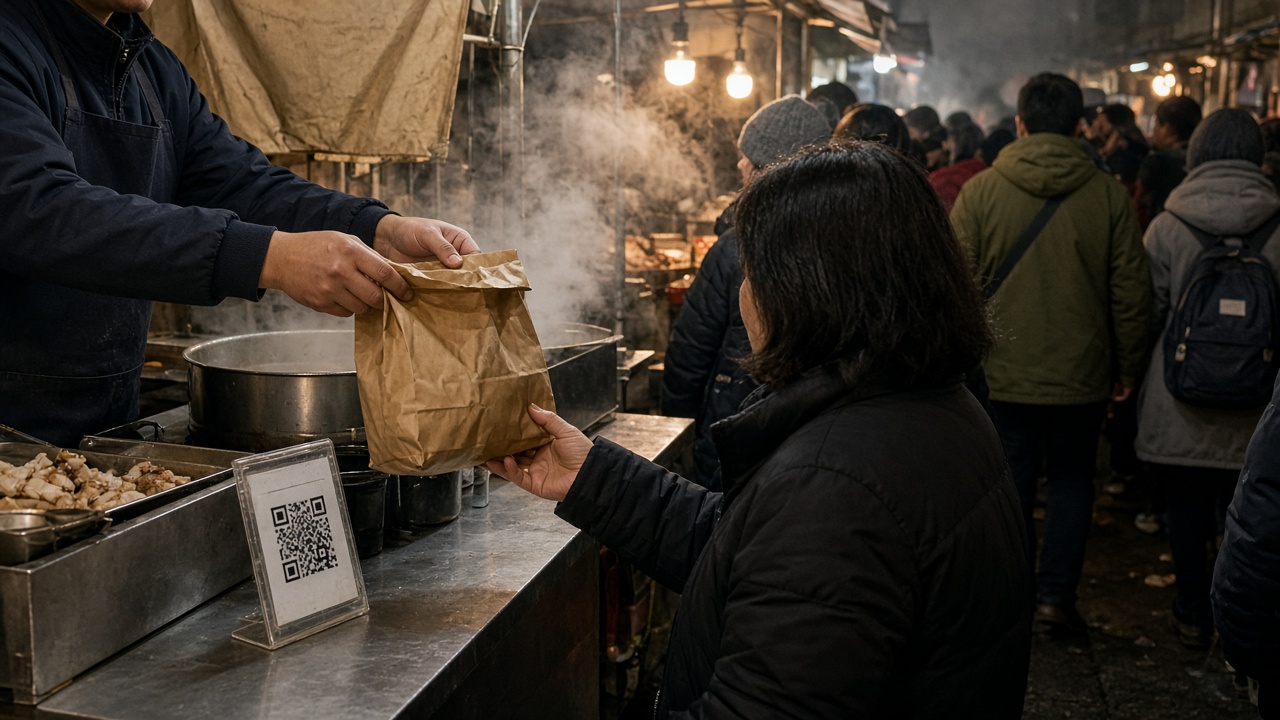
Shin Kong Commercial Bank Co. opened enrollment Saturday for a night-market QR settlement pilot that promises same-day ledger credits when shoppers pay with Taiwan Pay, according to terms stall owners in Taipei’s Ningxia and Raohe districts received from branch staff. The bank is targeting vendors who still deposit thick cash stacks on Mondays because consumer wallets mix convenience-store barcode apps with legacy electronic-payment accounts that settle on slower cycles.
How same-day payout works
Merchants who pass know-your-business checks receive a static QR linked to a Shin Kong merchant account. When a customer scans with a participating Taiwan Pay wallet, the bank routes the authorization through the Financial Supervisory Commission’s retail payment switch and books the net amount to the merchant balance by 11 p.m. the same calendar day, skipping the two-day float many aggregators keep for chargeback reserves.
Shin Kong caps per-transaction size at NT$3,000 to limit fraud exposure on open-air stalls. Vendors above NT$120,000 in monthly QR volume pay a 0.9 percent discount fee, lower than generic aggregator tables but higher than pure cash.
Why night markets now
Tourism bureau foot-traffic estimates showed night-market receipts rose during the Mid-Autumn long weekend even as daytime department stores reported mixed traffic. Stall associations asked banks for faster settlement so vegetable and seafood suppliers could be paid before dawn wholesale markets reopen.
Competing banks offer QR stickers but often settle on T+1 business days. Shin Kong’s pitch is calendar-day credit on weekends, when wholesale buyers still expect cash on Sunday night.
Fraud and chargeback rules
The pilot requires merchants to display a printed Shin Kong welcome sheet so customers can verify the legal name on the authorization screen. If a wallet user disputes a charge, the bank freezes only the disputed ticket, not the entire day’s batch—a change from older contracts that held 10 percent rolling reserves.
Branch staff warned vendors not to let strangers photograph QR codes to build fake listings on delivery apps, a scam pattern Taipei police flagged in August.
Who benefits inside the bank
Retail banking teams gain low-cost deposits from merchant balances that might otherwise sit in non-interest cash boxes. Treasury desks can sweep idle merchant balances overnight into short bills, sharing a sliver of yield if vendors opt in to a linked demand deposit.
Card center staff hope successful pilots convert stall owners to Shin Kong business credit lines for equipment upgrades—ice makers, vent hoods—though those loans are not bundled in Saturday’s announcement.
What regulators watch
The FSC has pushed interoperable QR standards so wallets do not fragment stall counters with six different stickers. Shin Kong’s pilot uses the Taiwan Pay logo but remains bank-branded; aggregators argue dual branding confuses tourists. Shin Kong said it will publish simplified Chinese and English stall leaflets before the pilot expands to Taichung in November.
For shoppers, the immediate change is operational: more stalls with bank-grade settlement speed, and for stall owners, a reason to keep QR receipts instead of counting coins after midnight.