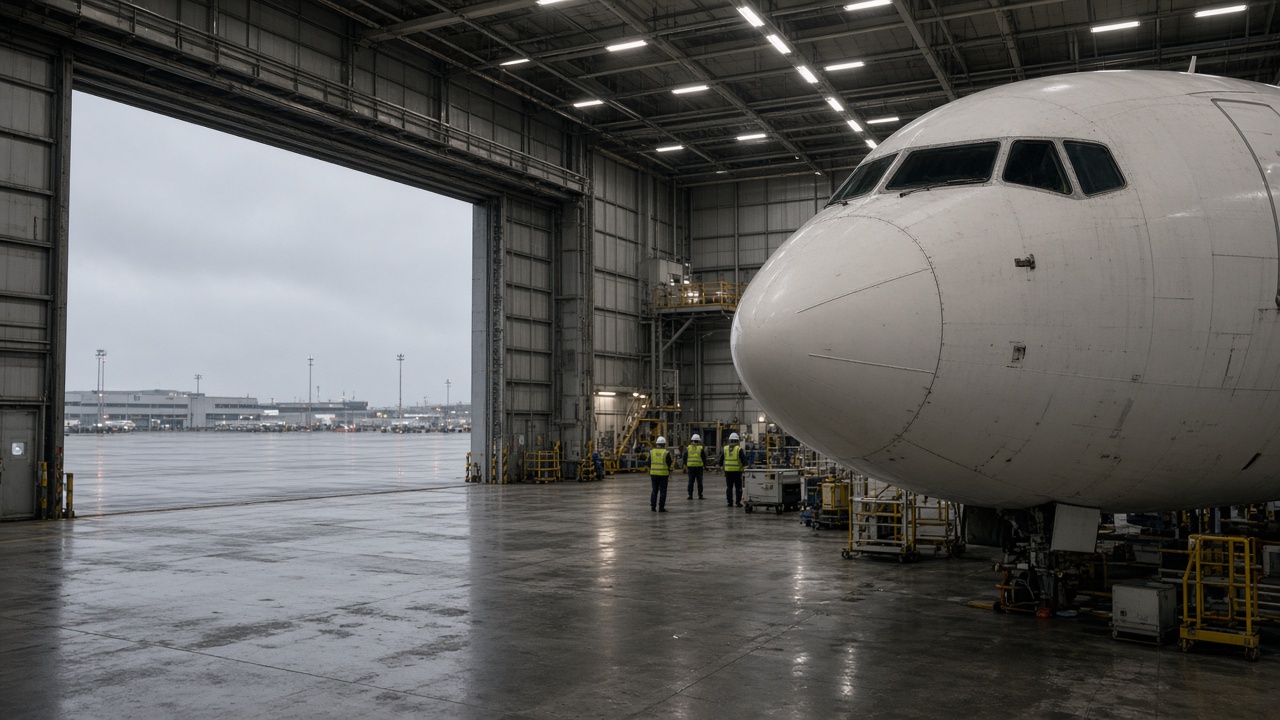
SIA Engineering shares jumped as much as 8.8 percent on Tuesday after DBS Group Research upgraded the aircraft maintenance provider to buy, citing renewed odds that parent Singapore Airlines will privatise a unit it already controls with about a 78 percent stake.
The call landed on a day the Straits Times Index slipped 0.6 percent to 3,059.04, with banks and the exchange operator weighing on the headline number while mid-cap industrials attracted stock-specific flows.
Why DBS likes the privatisation story
Analysts argued that SIA Engineering's listed status delivers little fundraising benefit when the flag carrier already owns the bulk of the equity. A take-private could simplify governance as SIA refreshes its fleet and outsources heavy maintenance checks across the region.
DBS said sluggish share performance over the past year makes a buyout cheaper for the parent, and that delisting would not strip Singapore of MRO capacity because the hangars and Changi tooling would stay put. Investors treated that as a catalyst, pushing volume to about 10.3 million shares versus a 30-day average under half a million.
Broader market moves
Biosensors International rose 5.7 percent after its partner Weigao disclosed a US$625.4 million buyout of a joint-venture stake in a stent maker, showing that medical-device deals still find buyers even when macro traders fret about bond yields. Singapore Exchange slipped 1.2 percent after its chief executive told a New York conference that blocked cross-border mergers should push the bourse toward Asian partnerships instead of US acquisitions.
Those cross-currents illustrate Tuesday's tape: index down, but stock pickers active on corporate-action angles.
Risks on the tarmac
Privatisation talk has surfaced before during aviation downturns and never guaranteed a deal. SIA must weigh minority shareholders, union concerns and regulatory scrutiny before any squeeze-out offer. Fuel prices, haze-related flight cancellations and Asian travel demand still drive maintenance hours more than banker slides.
For retail holders, the upgrade is a reminder to read circulars carefully if a formal offer emerges. The DBS target embeds a control premium; without a bid, the stock reverts to earnings multiples tied to global air traffic.
What to watch
Track SIA's next results briefing for capital-allocation hints, and watch whether Temasek-linked funds increase their float purchases. A confirmed go-private would shrink the STI's industrials slice, but Tuesday's volume shows traders are willing to front-run the possibility.
Aviation cycle
Changi passenger volumes have normalised after the Grand Prix week, but haze still forces occasional flight recalculations that trim maintenance hours. Traders pricing a privatisation premium must weigh those operational dips against long-term fleet renewal at SIA.
Regional peers such as ST Engineering also compete for third-party MRO contracts. A delisted SIA Engineering could bid more aggressively if it no longer reports quarterly margins to minority shareholders — another reason activists may resist a lowball offer.