Computacenter shares climbed to a record 5,190p on Monday after the Hatfield-based FTSE 100 reseller lifted its 2026 adjusted pretax profit target to at least £425 million, the fourth upgrade this year as AI data-centre customers kept placing orders.
The move added roughly £600 to the share price in a single session and pushed the company’s market value beyond £5.5 billion, a rare London-listed winner from the infrastructure spending behind generative AI. Chief executive Mike Norris told investors that North America and the UK both contributed to a third quarter that beat internal forecasts.
What changed in the trading update
In its statement on 26 October, Computacenter said group technology sourcing revenue grew strongly, driven by hyperscale and neocloud buyers building out capacity. Services revenue also rose year on year as professional services expanded, even as managed services revenue dipped slightly. Germany remained stable on an underlying basis, with management continuing a cost programme there.
The headline for shareholders was the profit floor. Analyst consensus compiled by the company stood at £387.1 million, with a top-end estimate of £395.3 million. Raising guidance to “no less than £425 million” signals management expects momentum to carry into the fourth quarter rather than pause after a busy September.
Backlog as the real story
Order backlog is the metric institutional holders quote on calls. Committed purchase orders against non-cancellable customer sales reached £12.6 billion at the end of September, up from £9.3 billion in late June. That figure measures invoiced gross income expected within 12 months, not vague pipeline slides, which is why the stock reacted more sharply than a modest earnings beat might justify.
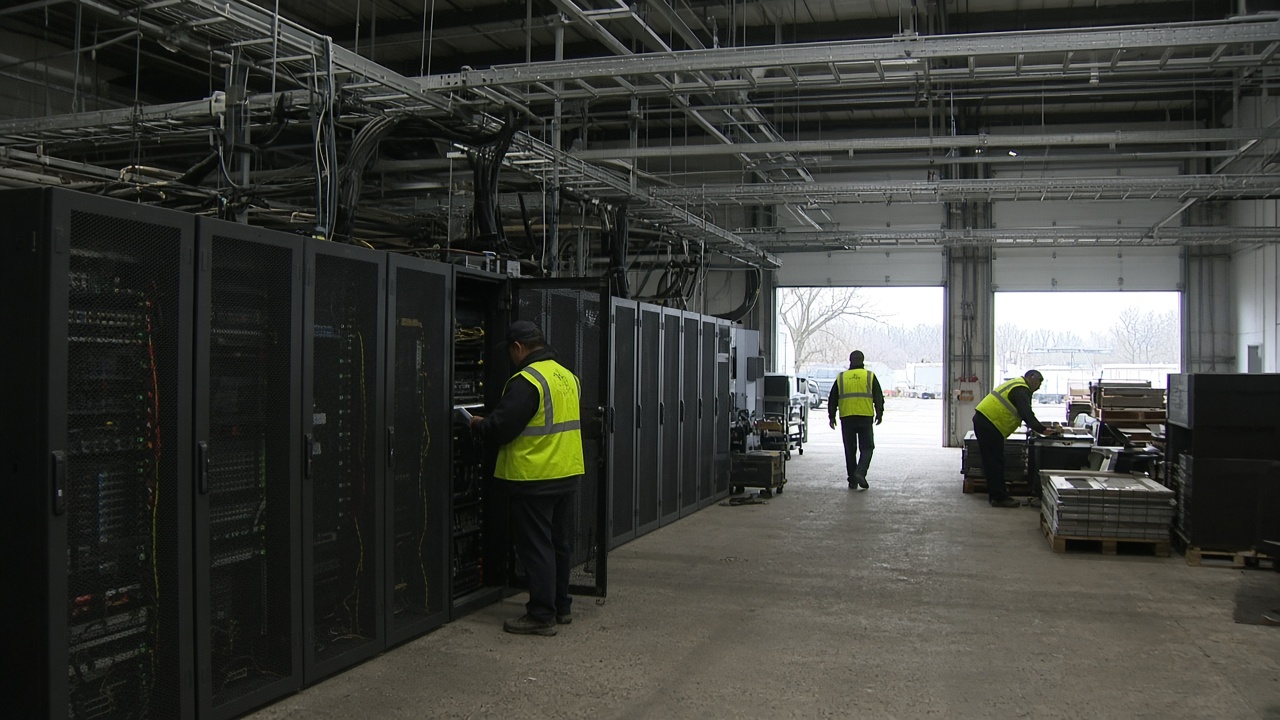
Hyperscalers and neocloud operators need integrators to source servers, storage and networking at scale, then configure kits in facilities such as Computacenter’s Hatfield integration centre. The group plans a capital markets day on 24 November at that site, including a tour of a new liquid-cooling facility aimed at dense AI racks.
London session read-through
Computacenter’s surge helped the FTSE 100 hold Monday’s gains into Tuesday’s pre-budget calm. Banks and defence names led the index on fiscal expectations, but CCC provided the clearest single-stock narrative for investors who want UK exposure to AI capex without owning US semiconductors directly.
Peer Kainos Group, a software-focused mid-cap, has also rallied this year, yet Computacenter’s hardware-heavy model benefits more directly from rack shipments. Short sellers have largely stayed away, according to exchange disclosures, reflecting how difficult it is to bet against a name tied to customer deposits for equipment already on order.
Risks on the horizon
Management cautioned that forward-looking statements depend on customer delivery schedules and vendor allocations. Any pause in US cloud capex would flow through backlog conversion months later. Germany’s restructuring could bite if European enterprise demand softens alongside higher rates.
Currency matters too. Much of the growth story sits in dollars, while the listing trades in sterling. A sudden pound rally could trim reported profits even if operational performance holds.
What comes next
The next scheduled update is a pre-close trading statement on 28 January 2027. Until then, investors will watch whether backlog continues to outpace revenue recognition and whether professional services margins hold as projects complete.
For UK fund managers benchmarking against a FTSE dominated by banks and oils, Computacenter has become the obvious AI-adjacent holding that still files in English and reports in pounds. Monday’s price action suggests that story still has buyers even after an 85 percent rally over twelve months.