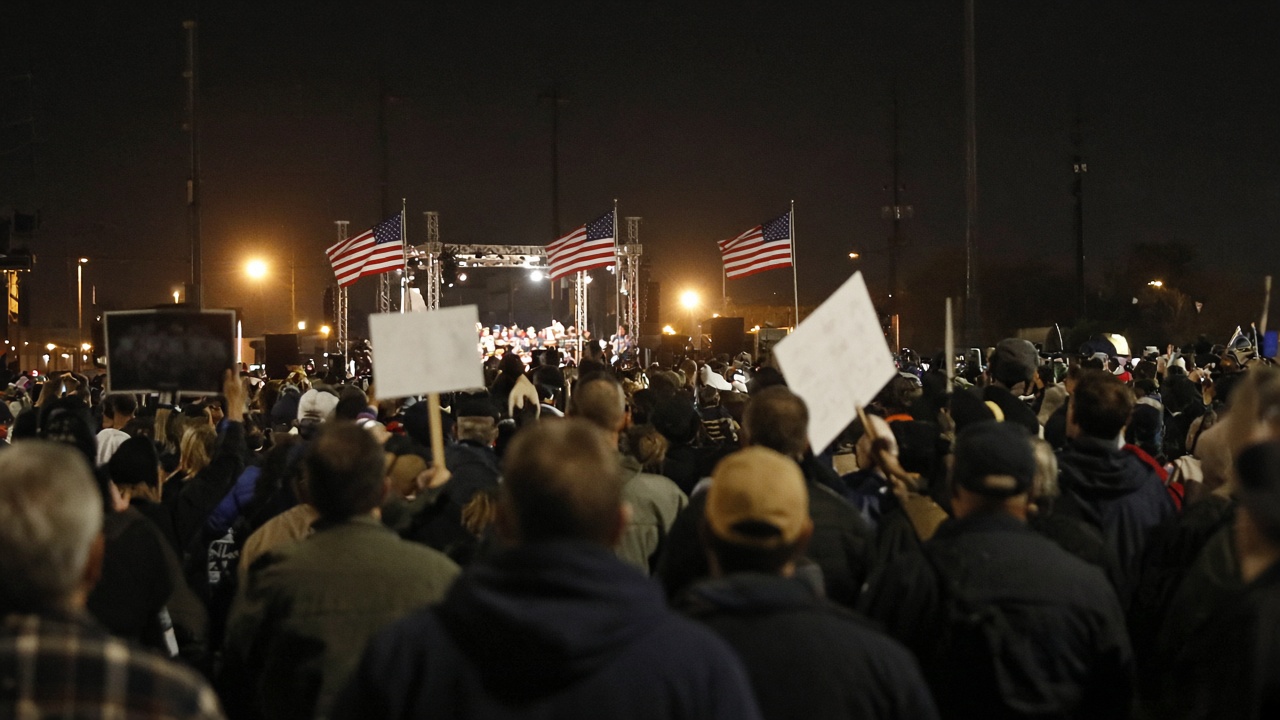
President Donald Trump told a Salina, Kan., crowd on Sunday night that re-electing Sen. Roger Marshall would put the Credit Card Competition Act on his desk, framing interchange fees as a household bill that merchants pass through at the register.
What the bill would change
The bipartisan measure, led by Marshall and Sen. Dick Durbin, D-Ill., would require banks with at least $100 billion in assets to enable at least one unaffiliated payment network on Visa- and Mastercard-branded credit cards, similar to the routing choice Congress mandated for debit cards. Merchant groups say central rate-setting by the card networks keeps swipe costs high; issuers counter that rewards programs and fraud tools depend on current economics.
Trump’s ninth public endorsement of the idea in 2026 landed two days before midterm voting in Kansas, where Marshall is on the ballot. He quoted savings as high as $2,000 a year for a typical family, while earlier remarks this year used a $1,200 figure. The Merchants Payments Coalition points to industry estimates that US swipe fees hit a record $198.25 billion in 2025 and that routing competition could shift roughly $17 billion annually toward lower checkout costs.
What cardholders should watch
Nothing in the rally changed law overnight. The Senate Banking Committee added cosponsors in August, and the House count stood at nine backers in September, but passage still requires floor votes in both chambers. If the act becomes law, the Federal Reserve would write implementation rules on which networks qualify and how issuers disclose changes.
Banks have warned that cheaper routing could trim funding for cash-back and travel rewards, especially on no-annual-fee cards that rely on interchange rather than interest income. Cardholders who carry balances face a separate risk: if issuers lose swipe revenue, some may raise purchase APRs or tighten credit limits, though that would unfold over statement cycles rather than immediately after a signing ceremony.
Separate fee hikes still hitting wallets
While Congress debates routing, issuers continue adjusting annual fees on airline cobrands. Citi and American Airlines said Oct. 27 that the AAdvantage Platinum Select and Business cards will rise to $150 from $99 at the first renewal on or after Jan. 24, 2027, pairing the increase with inflight Wi-Fi credits and Global Entry fee reimbursement. That change is contractual, not legislative — cardholders should read renewal notices and compare the new credits against the higher fee before auto-paying.
For shoppers, the practical split is simple: Marshall’s bill targets the invisible fee embedded in every card swipe, while the Citi refresh changes what you pay explicitly once a year for miles and perks. Track both, because either could alter the math on which card stays in your wallet in 2027.
How this differs from debit routing
Congress already forced debit routing choice after the Durbin amendment, and merchant advocates argue credit cards never received the same competitive pressure. Visa and Mastercard still set the interchange schedules their member banks charge, while independent networks such as Star or NYCE want a lane on credit transactions above the $100 billion asset threshold. The American Bankers Association has said the comparison to debit ignores higher credit fraud losses and chargeback costs that issuers absorb.
Retail groups reply that swipe fees climbed roughly 80% since the pandemic, outpacing wage growth and showing up in grocery and fuel prices because merchants embed the cost in shelf tags. Convenience store operators, who spoke at the Salina rally through trade association NACS, say interchange is their second-largest expense after payroll on many sites.
Checking your own statement
Cardholders will not see interchange on monthly statements; it is invisible to consumers but shows up in merchant pricing. If routing reform passes, watch for issuer notices about network logos on the card back, changes to rewards accrual rates, or new foreign transaction disclosures. Rewards chasers should screenshot current earn tables before any rulemaking comment period closes so they can compare after implementation.
Small-business owners who accept cards should also track processor statements: a drop in wholesale interchange could take quarters to flow through contracts, depending on whether you are on interchange-plus or flat-rate pricing.