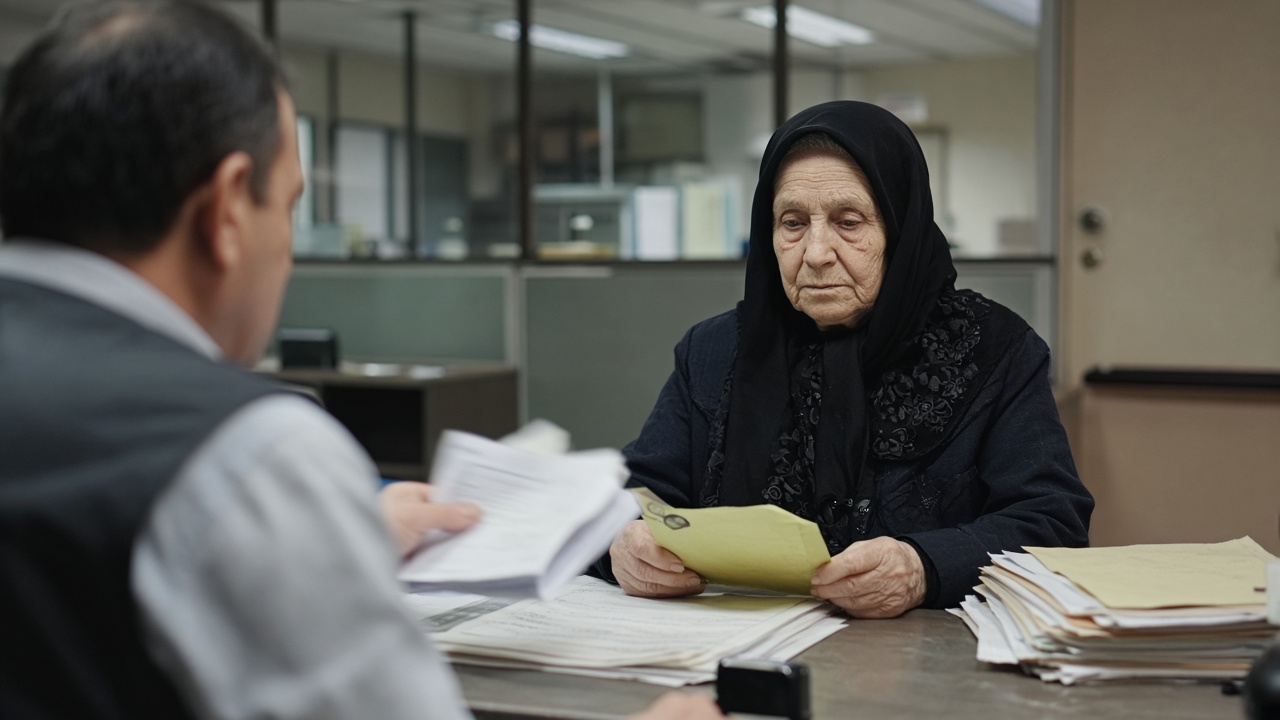
We should require Japan Pension Service offices to send itemized withholding slips to surviving spouses before December municipal tax filings—not summary letters that list only gross pension paid—because widows and widowers are filing refund claims without the deduction lines accountants need, and clerks are turning them away for “wrong forms.” Grief is not a compliance strategy; opacity is.
Generic totals fail when deadlines are rigid
Every autumn, pension recipients receive notices summarizing payments for the year. When a primary earner dies mid-year, survivors inherit fragmented records: employer retirement allowances, survivor basic pensions, and sometimes unfinished iDeCo transfers. Pension Service mail often states a single YTD figure without breaking out national income tax withheld per payment category—exactly the fields National Tax Agency templates expect on December filings at ward offices.
Tax assistance volunteers in Osaka and Sendai told InfoHandle they spend hours reconstructing withholding from bank passbooks because official slips arrived too late or omitted lines for survivor lump sums. A widow who misses December windows may still amend, but municipal inhabitant tax installments already billed assume the higher summary number—creating cash-flow shocks on fixed incomes.
What offices already know
Pension Service systems calculate withholding at source; the data exists in ledgers clerks see internally. Summaries are a print-format choice, not a technical impossibility. MHLW oversight reports have urged clearer survivor communications since 2011 disaster payouts exposed the same gap; little changed in envelope design.
NTA English pages describe which slips attach to which forms, but they assume recipients possess itemized certificates. Pension offices tell callers to “wait for January reissues,” which helps national income tax but not December municipal deadlines many prefectures enforce on pension-heavy households.
Strongest objection
Administrators say itemized slips could confuse recipients with multiple small lines. Confusion is worse when survivors guess. A one-page annex listing payment type, gross, withheld tax, and period beats a hotline queue that averages forty minutes in September.
Another objection: fraud risk if slips intercept mail. Survivor fraud exists, but so does under-refunding honest households who abandon claims. Registered mail for first itemized send is cheaper than court disputes.
What we are not saying
This editorial does not demand higher pension benefits—only paperwork fit for tax law. We are not blaming ward volunteers who follow checklists. We are saying the largest public pension administrator should treat survivor withholding as a December-ready product, not an January afterthought.
Concrete steps
Japan Pension Service should auto-generate itemized withholding slips within thirty days of death registration, mirroring employer gensen formats. MHLW should tie performance metrics to December filing success rates for survivor households, not call-center volume alone. Ward offices should accept provisional filings when itemized slips are postmarked before deadline—policy NTA can clarify with one circular.
Until then, survivors should photograph every pension deposit line and request written withholding breakdowns by registered mail—not verbal totals by phone. Public institutions owe widows clarity before December, not apologies in January.
Volunteer burden
Free tax-aid societies report volunteer burnout when September queues fill with survivors holding summary letters only. One Sendai clinic turned away walk-ins last week not from lack of sympathy but from liability rules forbidding guesses on withheld amounts. Itemized slips would shrink those lines and let volunteers focus on complex inheritance splits instead of reconstructing passbook lines line by line.