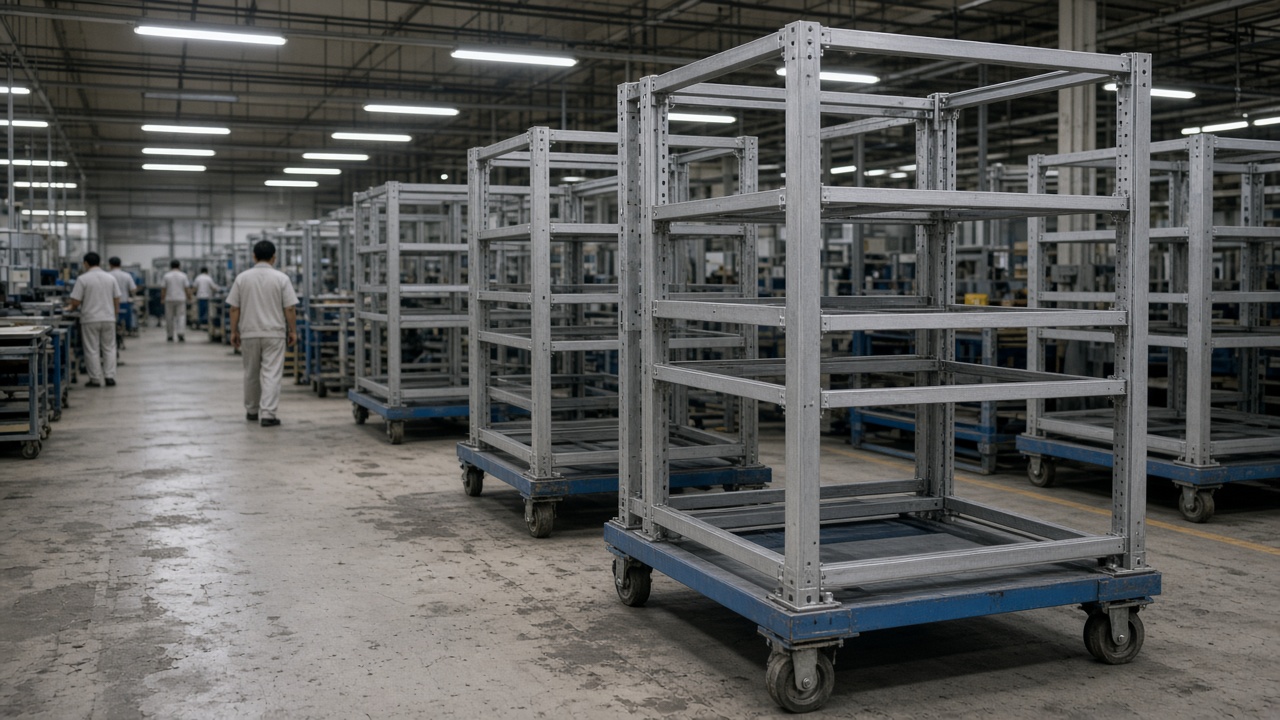
Hon Hai Precision Industry told the Taiwan Stock Exchange on Friday that it expects November consolidated revenue to land roughly flat compared with October, even as parent Foxconn keeps winning AI server rack orders that are eating floor space once reserved for smartphone final assembly.
The filing matters because Hon Hai remains the heaviest-weight single name in many retail portfolios, and any hint that handset volumes are stalling can move the cap-weighted gauge even when chip foundries are setting price records. Analysts at Yuanta Securities said the guide implies rack and liquid-cooling chassis lines are running near full utilization while legacy phone SKUs wait for carrier subsidy windows that typically open closer to Lunar New Year.
What the exchange filing actually said
In its monthly revenue notice, Hon Hai said October consolidated sales reached about NT$186 billion, up from the prior year on AI-related build-to-print work. For November, the company pointed to “similar scale” revenue without publishing a precise range, a phrasing Taiwan issuers often use when order books are firm but product mix is shifting faster than finance teams can model.
Investors read that as a signal that Foxconn Technology Group is prioritizing margin-rich AI infrastructure over low-margin handset shells. Two contract manufacturing peers with smaller AI exposure guided low-single-digit November declines in separate filings this week, which makes Hon Hai’s flat call stand out.
Rack demand versus handset seasonality
Server rack shipments tied to U.S. hyperscaler capex have stayed elevated since midsummer, according to supply-chain checks published by TrendForce. Those checks show Hon Hai’s Taoyuan and Kaohsiung campuses running extra shifts on rack integration even as North American customers delay some consumer electronics launches.
Handset lines are not idle — the same checks note ongoing work on foldable prototypes and midtier 5G models for Japanese and European brands. But the mix tilt means Hon Hai can keep revenue steady without matching last year’s November handset surge, when carriers pushed year-end upgrades before tax incentives expired.
Investor read-through for Taiwan listings
Fund managers said the guide supports the view that AI hardware demand is offsetting consumer softness in Greater China retail channels. They cautioned, however, that flat revenue at Hon Hai still depends on timely GPU tray deliveries from Nvidia and AMD partners; any customs delay on high-end accelerators would show up quickly in Hon Hai’s weekly shipment tallies.
Hon Hai shares finished Friday down slightly with the broader market after touching an intraday high earlier in the session. The company’s next detailed outlook is expected with its quarterly briefing in mid-November, when executives typically break out cloud versus consumer revenue for the first time after auditor review.