On 24 November 2024, Taiwan CPC told drivers that international crude had pushed the weekly formula to raise gasoline by NT$1.1 per liter and diesel by NT$1.3. At midnight on the 25th, the reference board for 95 unleaded gasoline stayed at NT$30.1. Gasoline did not move at all; diesel rose only NT$0.1 to a reference of NT$27.2 per liter. The company had already swallowed the entire gasoline increase before the price reached the pump.
The board that did not move
That week's arithmetic is printed in every CPC price release, and the Central News Agency carried the same numbers: the 7D3B benchmark (70 percent Dubai, 30 percent Brent) had climbed US$1.22, the Taiwan dollar weakened NT$0.089 against the US dollar, and the published pass-through worked out to a 1.58 percent increase. Under the floating-price rules, gasoline was supposed to rise NT$1.1 per liter compared with the prior week's reference retail price.
Drivers who fill up on 95 unleaded saw none of it. The headline product remained NT$30.1 per liter while super diesel ticked up a single dime. CPC said it had activated the dual stabilization mechanism, absorbing NT$1.1 on every liter of gasoline and NT$1.2 on diesel, matching the formula totals on paper while changing almost nothing on the board.
Social messages every Sunday night focus on the delta: up a dime, down two. The more interesting row in the press release is the one labeled should adjust, which can be more than a dollar while the delta is zero. The gap is not a clerical error. It is where Taiwan's two post-formula brakes do their work.
If you read only the headline change, the November week looked boring. If you read the should-adjust row, it was one of the louder weeks of the year. That split is normal whenever both brakes bind at once.
What the formula runs before any brake
Every week CPC still starts from the same published recipe it has used since the 7D3B blend entered the system in September 1996: take Platts-reported Dubai and Brent, weight them seventy-thirty into a weekly average, compare it with the previous week, translate the move through the exchange rate, and pass through roughly eighty percent of the change before taxes and fees turn the result into a retail should-adjust figure. A trial floating regime began on 26 September 1995; the current blend of benchmarks dates to 1996, according to a Control Yuan investigation report that walks through each revision.
When the economy ministry abolished the statutory oil price formula on 11 September 2000, Formosa Petrochemical entered as a competitor, but CPC's transparent weekly worksheet remained the market clock. Formosa tracks the same reference moves; the brakes described here are applied through CPC's releases and the policy caps that bind the state-owned supplier most visibly.
Ministry-backed explainers note that the eighty percent pass-through deliberately excludes fixed costs such as payroll and depreciation, so the formula row already skews toward consumers before politics enters. Even that softer number is not what you pay until the two caps below finish with it.
Republic of China year 113 releases also mention a temporary commodity-tax reduction embedded in the weekly tables (NT$2 per liter on gasoline and NT$1.5 on diesel in the 2024 announcements). That tax line is a third column in CPC's spreadsheet, separate from the neighbor and NT$30 brakes. This story focuses on the two stabilization layers because they can erase an entire formula move after tax.
CPC announces the outcome for the coming week at zero hours on Monday after running the worksheet over the prior seven days of 7D3B and exchange data. Private stations set their own promotions, but the reference change anchors the island because wholesale deliveries are priced off the same reference.
Brake one: stay below the cheapest neighbor
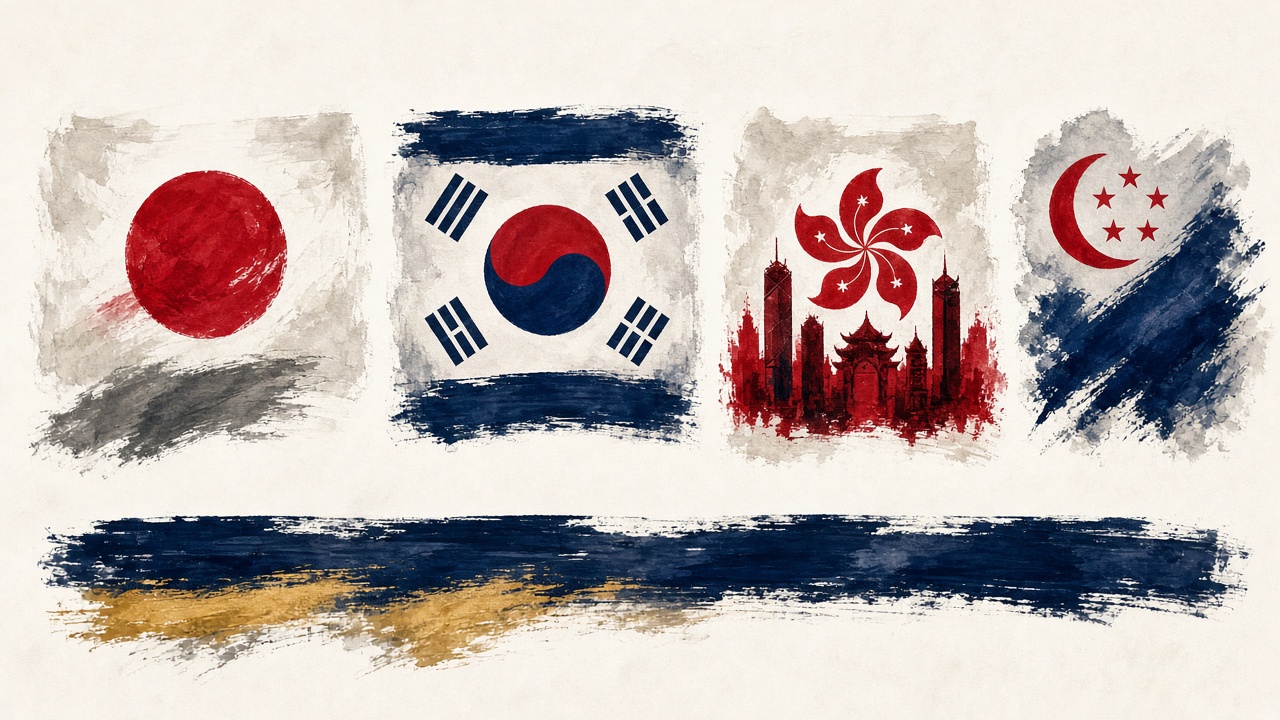
The first brake is external. An Executive Yuan table on the dual gradual-increase mechanism states that domestic gasoline and diesel may not exceed the lowest pre-tax wholesale price among Japan, South Korea, Hong Kong, and Singapore. When the formula would push Taiwan above that neighbor floor, CPC absorbs the gap so the posted price stays underneath.
In the November 2024 week, that neighbor cap ate NT$1.0 per liter on gasoline and NT$1.1 on diesel before anything else happened. CPC publishes a weekly comparison table on its website so anyone can check which neighbor set the ceiling.
The cap can also interact oddly with falling international markets. On 30 June 2024, CPC said the formula implied gasoline should rise NT$3.3 per liter and diesel NT$4.7 because the 7D3B average had climbed US$0.85 and the calculated pass-through was 1.07 percent. After the neighbor cap and the second brake, the company absorbed NT$3.5 on gasoline and NT$4.9 on diesel, yet the retail reference prices fell NT$0.2 per liter for both fuels. The formula pointed up; the posted price moved down.
Policy writers sometimes describe the neighbor rule as a competitiveness guardrail. Taiwan wants to remain the cheap fill-up in East Asia on a pre-tax basis even when that requires CPC to eat margin. The guardrail is not approximate. The absorption liters are listed beside it every week.
When international prices collapse, the neighbor brake can sit idle. A Ministry of Economic Affairs release describing autumn 2025 adjustments said proposed decreases already kept Taiwan below Japan, South Korea, Hong Kong, and Singapore, so that week's table showed no neighbor absorption even though the year-to-date stabilization line for 114 still read NT$63.21 billion through September.
Brake two: the NT$30 ladder on 95 unleaded
Once 95 unleaded retail crosses NT$30 per liter, a second table kicks in. Between NT$30 and NT$32.4, CPC must absorb twenty-five percent of any further increase (rounded). Between NT$32.5 and NT$34.9, it absorbs half. Above NT$35, CPC and the government together absorb seventy-five percent. The National Development Council told legislators in April 2024 that this oil price stabilization measure runs alongside the neighbor cap as the dual gradual-increase mechanism.
November's gasoline was already above NT$30, so the second brake took another NT$0.1 per liter even after the neighbor absorption. Add the two stacks and you get the NT$1.1 total, exactly the formula increase, entirely on CPC's account.
按浮動油價機制調整原則,汽、柴油應調價格與參考零售價格相比,汽、柴油應各調漲1.1元及1.3元,但為維持價格低於亞洲鄰近國家,汽、柴油各吸收1.0元及1.1元
The tiers turn psychology into math. Drivers notice whole-dollar thresholds. Holding 95 unleaded near NT$30 even when Brent moves has become a political commitment as much as a spreadsheet outcome, which is why the second brake only activates after the first cap already failed to keep prices low enough.
February 2024 added a short-lived holiday column: CPC's Lunar New Year releases tracked extra absorption under a separate only-fall-never-rise row while the ordinary dual brakes kept running underneath. Once the holiday window closed, the spreadsheet returned to the two standard caps alone.
Where the missing dollars sit on CPC's books
CPC repeats one accounting line in nearly every release: cumulative absorption on gasoline and diesel stabilization. It started 2024 at NT$9.97 billion through January, rose to NT$53.70 billion by March, NT$129.43 billion by May, NT$204.09 billion by July, NT$223.88 billion by September, and NT$235.31 billion through October, the figure attached to the November case study.
The Ministry of Economic Affairs republishes the same language on its site, which makes the series easy to audit even if you never read a trade paper. The Ministry of Justice mirrored the October 2024 release as well, word for word on the dual mechanism paragraph, which shows how central the wording is to the administrative record.
By August 2025 (Republic of China year 114), the cumulative line had reached NT$59.04 billion; by September it stood at NT$63.21 billion. The calendar reset makes the 114 figures look smaller than 113's autumn peak, not because the brakes stopped working.
Those weekly gasoline and diesel totals are only part of CPC's balance sheet pain. The company's 2024 annual report states that policy absorption across gasoline, diesel, natural gas, and liquefied petroleum gas reached about NT$737 billion for the year, contributing to a pre-tax loss of about NT$355 billion. The Legislative Yuan's budget review puts the net loss at about NT$341 billion with accumulated losses of about NT$1,203 billion. Different definitions, same direction.
Domestic gasoline sales alone were 7,664 thousand kiloliters in 2024 per the annual report. Multiplying liter-level absorption by that kind of volume shows why the stabilization lines hit billions quickly even when the pump moves a dime at a time.
Compare the October cumulative NT$235.31 billion gasoline and diesel line with the NT$737 billion all-fuel absorption in the same annual report and you see what else CPC subsidizes beyond the forecourt: natural gas for power and homes, bottled gas for kitchens. Drivers feel only the automotive slice, but auditors treat the whole package when they ask whether stabilization is sustainable.
None of that bookkeeping removes the weekly worksheet from public view. The same release that announces a frozen NT$30.1 board still lists how many liters CPC ate to keep it there, which is why the case study numbers above come from journalism and company statements rather than leaks.
TIER policy analysts have long noted that Taiwan's pre-tax pump prices look cheap against Tokyo or Seoul only after you account for what CPC absorbs in the worksheet; the neighbor cap encodes that comparison every week instead of leaving it to editorial charts.
Why the totem can freeze while crude keeps swinging
Critics at the Legislative Yuan Budget Center argue that perennial absorption bleeds a state-owned refiner that is also supposed to fund energy transition, and the widening losses show up in their 113-year CPC review. Supporters of the caps reply that visible stabilization is the point: the neighbor ceiling and NT$30 tiers are deliberate shock absorbers for drivers who see fuel as a daily expense.
Either way, the mechanism is not a secret subsidy whispered at the pump. It is a published sequence, formula, neighbor cap, NT$30 ladder, printed every week with liter-by-liter absorption tables. When 95 unleaded stayed at NT$30.1 on 25 November 2024, the board was telling the truth. The formula's NT$1.1 increase had died in the paperwork first.