CPC Corp., Taiwan and Formosa Petrochemical Corp. are shortening the tenor on dollar hedges and leaning harder on syndicated bank lines as the New Taiwan dollar slips against the U.S. currency, raising the financing bill on crude that both refiners must buy in dollars even when they sell fuel at home in NT dollars.
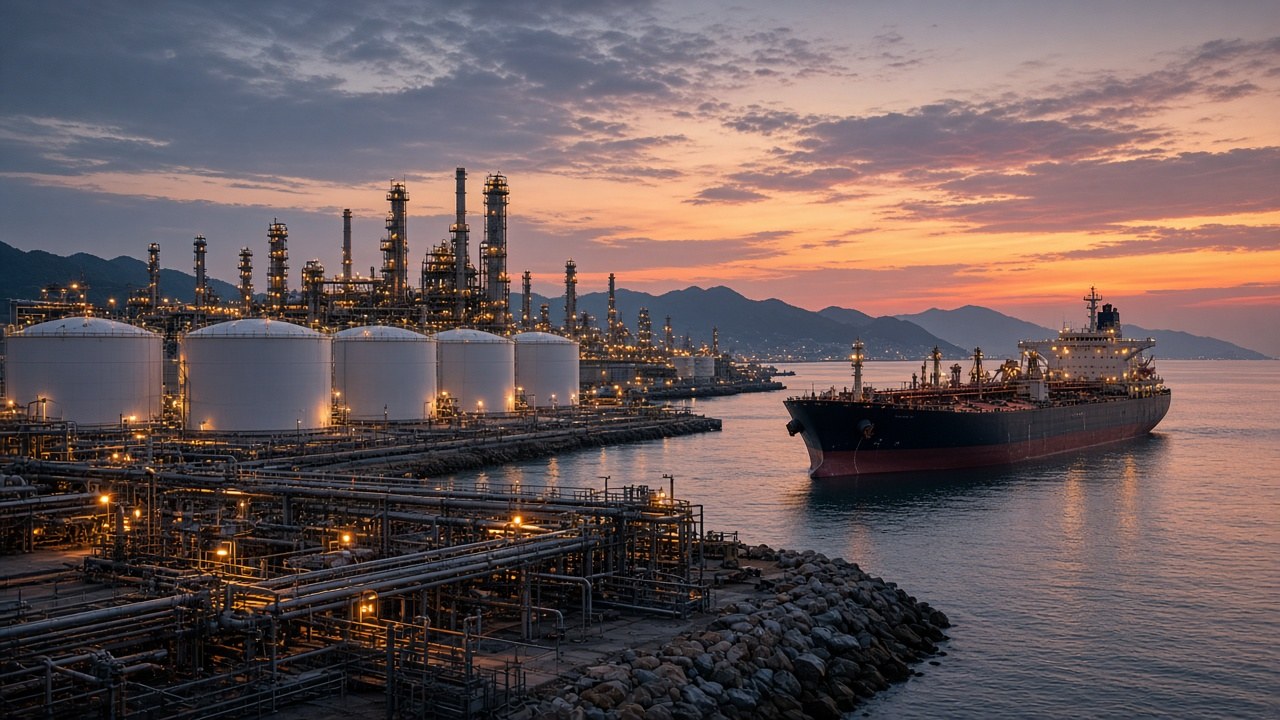
The shift is less about spot Brent, which has traded in a narrow band this month, and more about the cross-currency mismatch that Taiwanese refiners live with year-round. CPC, which runs the island's only state-owned refinery network, imports roughly 400,000 barrels per day of crude and condensate, according to its latest operational disclosure. Formosa Petrochemical, the listed arm of the Formosa Plastics Group, sources similar volumes for its Mailiao complex in Yunlin County. Every cargo is priced in dollars; working-capital lines and hedge settlements still run through U.S. funding markets that have not fully priced in rate cuts.
What the balance sheets show
In CPC's first-half 2026 management report filed with the Ministry of Economic Affairs, management flagged "foreign-exchange volatility on crude payables" as a margin risk alongside maintenance at its Taoyuan and Kaohsiung units. The company said it had increased the share of three-month forward contracts versus six-month covers, accepting more roll risk to avoid locking in wider basis points on longer-dated swaps.
Formosa Petrochemical told investors on its August call that dollar liquidity costs rose "modestly" in the second quarter even as utilization at Mailiao held above 90 percent. Chief Financial Officer Huang Chih-yung said the company would keep gross debt stable but might draw more on NT-dollar revolving credit from Taiwan's megabanks when the spread between dollar Libor-style benchmarks and local funding favors it—a tactical choice, not a structural de-dollarization.
Local lenders including Bank of Taiwan and Mega International Commercial Bank have been marketing trade-finance packages to energy importers since the central bank, the CBC, reminded the market in July that it would intervene if disorderly NT-dollar moves threatened import prices. Refiners are natural clients: long payment cycles, predictable collateral in stored crude, and government oversight that reduces credit anxiety.
Hedging desks and the Fed path
Treasury teams at both companies typically layer currency forwards over crude price hedges managed in Singapore and Houston. When the Federal Reserve held the policy rate steady at its September meeting while signaling fewer cuts in 2026 than traders had hoped, dollar funding stayed expensive relative to pre-2022 norms. That shows up not in headline crude quotes but in the all-in cost of a three-month dollar loan rolled twice before a Golden Week maintenance window.
Energy traders in Taipei said CPC had been more active in the onshore FX swap market in the two weeks before this story, a pattern that often precedes large crude settlements. Formosa's desk, by contrast, has favored offshore nondeliverable forwards through its usual international banks, according to two people familiar with the flow who asked not to be named because they are not authorized to speak publicly.
Neither company is facing a liquidity crisis. CPC carries implicit state support; Formosa Petrochemical reported NT$28.4 billion in cash and equivalents at June 30. The issue is incremental: each 0.5 percent move in the NT dollar against the U.S. dollar on unhedged payables translates into tens of millions of NT dollars on a quarterly cargo program.
Pump prices and the Golden Week schedule
Retail fuel prices in Taiwan are adjusted weekly under a formula that includes international crude and the NT-dollar exchange rate. CPC sets the ceiling that private stations follow; Formosa's retail arm competes on service and location rather than openly undercutting the state formula. If dollar financing costs persist, the pass-through debate inside the Ministry of Economic Affairs intensifies—especially with the Mid-Autumn Festival and Golden Week travel approaching, when diesel demand for buses and trucks spikes.
Maintenance at Formosa's No. 3 cracker and associated units is scheduled for late September, which will temporarily reduce internal consumption of naphtha but not the need to settle dollar invoices on crude already on the water. CPC plans partial shutdowns at Kaohsiung for catalyst work, tightening local supply of certain distillates for a week, according to a notice posted to its procurement portal.
What comes next
Refining margins in Asia have improved from the lows of early 2025, but Taiwanese operators remain mid-pack on complexity versus newer Middle East and Chinese plants. Financing is not their largest cost line—crude itself is—but it is the one executives can adjust week to week. The incentive is to keep hedges short, borrow locally when the CBC steadies the NT dollar, and avoid being caught with six-month dollar locks if the Fed delays easing into 2027.
For industrial buyers and airlines, the practical watch item is still the weekly pump notice. For CPC and Formosa Petrochemical, the quieter line item is the FX swap ticket: who rolls it, at what spread, and whether Golden Week turnarounds coincide with another dollar squeeze.