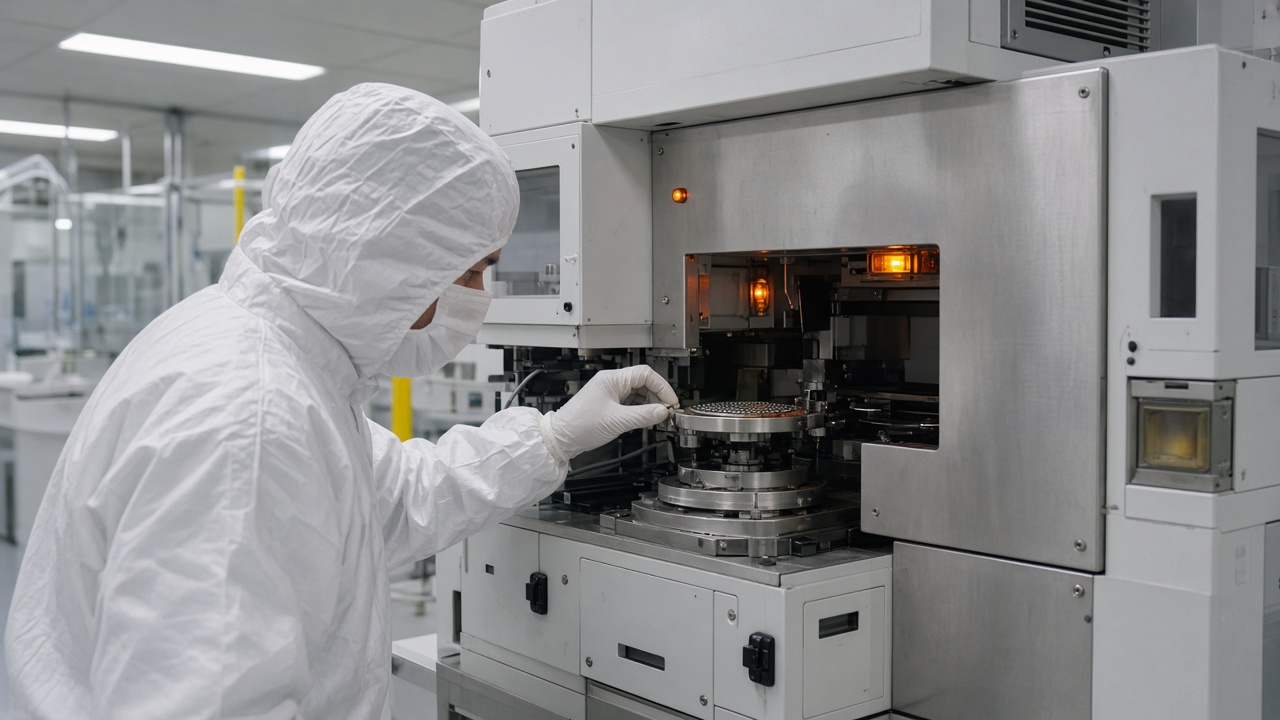
Hanmi Semiconductor told investors in a closed briefing that its bonding-tool order book for high-bandwidth memory lines has grown faster than the Kospi equipment peer group expected, with an Ulsan backend support hub now staging fluxless and hybrid bonder installs for SK Hynix’s southern fabs while main TC production stays anchored in Incheon. CFO Kim Jung-young reiterated on the call—parts of which were described to InfoHandle by two attendees—that Hanmi aims to secure essentially all thermal-compression bonder demand for HBM4, the stack generation memory makers plan to ramp later this year.
Ulsan hub versus Incheon fabs
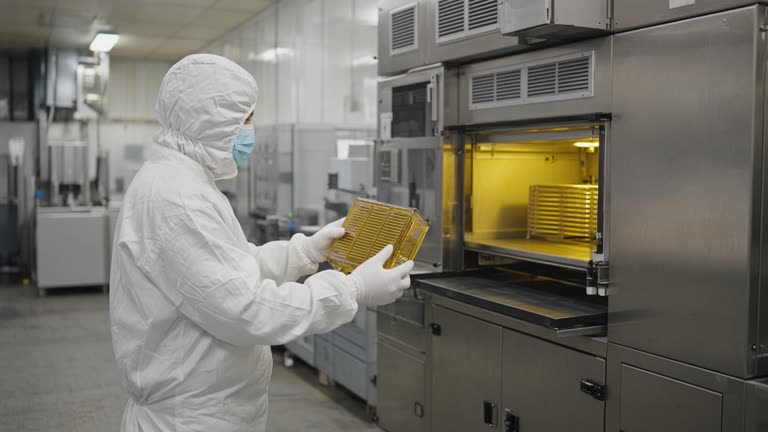
The Ulsan site is not a greenfield factory; Hanmi is leasing clean-room bays near existing memory backend contractors to shorten install cycles and keep field engineers closer to HBM4 pilot lines. Technicians are pre-commissioning TC BONDER 4 units and early fluxless tools before cranes move them into customer fabs, reducing downtime when clean-room floors are already crowded with packaging retrofits. Incheon remains the volume spine—Factory 7, a 28.5 billion won hybrid-bonder plant disclosed in June, is scheduled to run from August 2025 through November 2026—but Ulsan is where acceptance tests tied to customer yield targets are increasingly run.
Hanmi’s board approved Factory 7 to answer next-generation premium HBM demand; the Ulsan hub handles the messy middle: software revisions, spare bond-head inventory, and overnight swap-outs when a single bonder misaligns a 16-high stack. Memory makers rarely publicize those stoppages, but they show up quickly in Hanmi’s service revenue line.
Product stack and JEDEC height
Hanmi began mass production of TC BONDER 4 in July, betting that relaxed JEDEC stack-height rules let thermal compression stay competitive against hybrid bonding for HBM4. Company releases say the tool improves productivity and precision versus rivals; Evertiq reported management expects active use in global customers’ HBM4 lines. BusinessKorea quoted Kim saying Hanmi is the only Korean vendor testing HBM4 bonders with customers and one of only two or three globally.
Fluxless TC bonders—ordered for next-generation stacks—are slated for first delivery within 2025, Kim said at a July strategy session in Seoul’s Yeongdeungpo district. The Ulsan hub is where those units get final calibration before handoff, because humidity and vibration profiles closer to customer sites catch issues Incheon’s floor might miss.
Kospi tape and the won
Hanmi shares have outpaced the Kosdaq equipment index on HBM4 optimism, though a stronger won against the dollar trims the translation of overseas tool quotes. Traders said any delay in SK Hynix’s HBM4 mass production would be the first thing to unwind the rally; conversely, a second U.S. memory customer adding Hanmi bonders would extend backlog visibility into 2027. Order book swelling does not automatically mean revenue this quarter—tools ship on acceptance—but it locks capex plans at customers who might otherwise dual-source.
Analysts on the Seoul call pressed Kim on margin mix between TC and hybrid bonders. He answered that hybrid tools carry higher ASPs but longer install cycles; Ulsan staging is meant to protect TC margins by cutting field-service days. Hanmi did not disclose exact order counts in the briefing.
What to watch before Friday close
Disclosure watchers expect Hanmi’s next quarterly filing to break out HBM-related revenue and Factory 7 spend. Until then, Ulsan bay occupancy and Incheon crane schedules are the tangible signals. If fluxless units clear acceptance before Chuseok, Hanmi’s winter revenue guide could jump; if memory fabs pause tool hookups for holiday staffing, the hub becomes a parking lot—not a catastrophe, but a story the Kospi will punish quickly.
Equipment leasing firms in Ulsan said Hanmi prepaid bay deposits through March, signaling confidence in SK Hynix’s backend schedule. Rivals in Japan and the Netherlands still pitch hybrid bonders, but Hanmi’s near-monopoly on HBM3E TC tools gives it pricing power on service contracts that can outlast individual tool sales. Investors on the Yeongdeungpo call asked whether Ulsan might become a permanent second campus; Kim answered that Incheon remains the capex anchor while Ulsan is “customer-adjacent staging,” language the Kosdaq will parse until cranes actually move north.